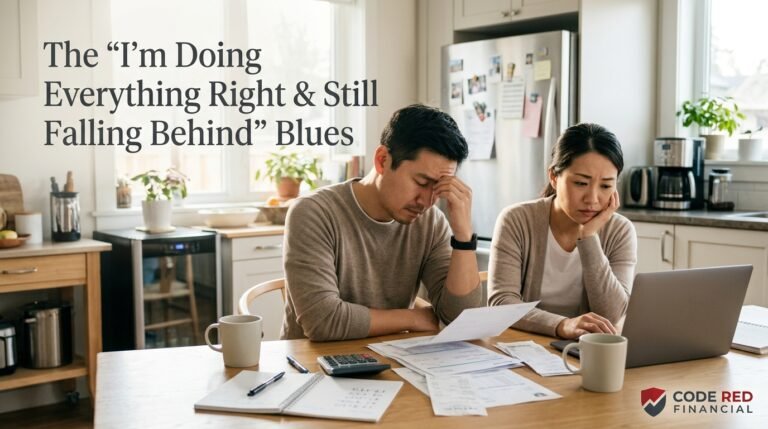
It feels like a perfectly ordinary afternoon, and you are standing in the kitchen with a grocery receipt in one hand and your phone in the other, scrolling back through last year’s shop because you are certain you must have misread something. Sadly, you have not, although it appears that way, doesn’t it? Listen, I go through the after-grocery shopping depression like just about everyone else, even though I am not living paycheck to paycheck. I am simply extreme bean counter, and somewhere between the cost orange juice and the olive oil that dreaded financial stress feels like a 50-pound weight sitting on your chest.
Listen at some time or another we all have done the spread sheet or a simple expense report jotted down on a loose piece of paper or in a budgeting app right and made coffee at home for so long that we can barely recalled what an actual café smelled like. And yet even with the added responsibilities at work you happen to have taken on, the financial strain persists like that stubborn pimple during the teenage years. Reminds me of an old sitcom in the United Kingdom many years ago called “Keeping up Appearances”. That tends to be what many people are doing these days, well, it feels that way any way. And judging from the rise in household debt, that very well might be so. I have heard folks being startled by their utility statement of late, believing that the amount on must belong to someone else’s house, with many pondering what on earth they are supposed to do that have not already been done. The frustration is real.
If that situation feels uncomfortably familiar, let’s start with something no budgeting app will ever say: you are not the problem.
For a long time, the advice was gloriously simple right, Study hard, work hard, spend less than you earn, save a little every month, buy a home, and let time do the rest. It was a sensible map, and it served those who followed it well, but it was drawn for a landscape that has since been reshaped beneath our feet. Housing, energy, food, insurance, childcare and rent have all climbed, for a great many households, far faster than wages and the gap between the two has been filled by the one resource nobody can manufacture more of, which is your own energy and attention.
When the numbers stop adding up, it’s worth taking a moment before defaulting to the usual explanation—that you just haven’t been disciplined enough. Skipping a few lattes won’t cover a rent hike or a housing market that’s moved far beyond what normal salaries can afford, and pretending it will isn’t smart budgeting. It’s more like a harsh kind of accounting.
What many of us are feeling, I suspect, is a form of collective grief. We are mourning the milestones we were promised, the front door of our own, the comfortable savings account, and the confidence of knowing that a broken boiler would be an irritation rather than a crisis. Watching those things drift further away whilst being told to try harder is exhausting for so many and in a way that has little to do with money and a great deal to do with feeling unseen, and it tends to land hardest on the conscientious, the people who read the articles, keep the receipts and follow the rules to the letter, that is in my opinion any way and If you are exhausted by it all, you are not being dramatic, to a degree it makes perfect sense.
This isn’t the doom and gloom section of the internet, so I would like to suggest a different frame, which is to think of your finances less as a scorecard and more as a set of defense mechanisms. A defense mechanism does not ask whether you are good or bad with money. It asks what will let you sleep tonight, and what will stop the next surprise from becoming a spiral. A small buffer, an automated transfer, a bill you have renegotiated, a rule that says no large purchase without a night’s sleep, each of these is a modest wall against chaos, and each protects something far more valuable than a balance, which is your peace of mind.
Traditional budgeting carries an unspoken moral judgement. Every line item becomes a verdict and every overspend a small confession, and so we turn the whole exercise into a test of character that we always seem to be on the verge of failing. The trouble is that shame is a poor motivator and an even poorer strategist, because it makes us avoid the very statements and screens that might help us.
You cannot control interest rates, rents or the price of a weekly shop. You can, however, decide how much of that turbulence reaches your nervous system, and that is a form of financial control that no one can take from you.
We are typically very good at checking balances and sort of poor at checking what those balances are doing to us. These three habits are small enough to begin this week.
The first is to keep a weekly money-and-mood note. Once a week, spend five minutes writing down your account balance and, beside it, a number from one to ten for how anxious you feel about money. Over a month, patterns begin to appear. Perhaps the worry peaks the day before payday, or after an evening of scrolling through other people’s holidays, or whenever one particular bill lands on the mat. Stress that has a number and a date attached becomes something you can examine rather than something that simply happens to you.
The second is to build one defence against your loudest worry, and only one. If your greatest fear is the unexpected bill, start a small calm fund with whatever you can spare, even if it is the price of a sandwich, because the habit matters far more than the sum at this stage. If it is the energy statement, give yourself one evening to compare tariffs or to ask your provider what support is available. A single worry properly dealt with frees more mental space than a dozen half-managed ones, and it gives you the evidence that your effort does count for something.
The third step is to reset the scoreboard. The goalposts have shifted, and chasing the old ones will only leave you worn out. Define success in ways you can actually control, like resilience, options, and your direction of travel. Ask yourself if you’re a bit better prepared than six months ago, and whether you have more choices now than before. If owning a home is still the dream, make it a direction rather than a deadline, and let smaller wins along the way—like your first month with a buffer or the first bill you no longer dread—count as the real progress they are.
It is important to keep in mind that your worth was never listed on the Balance Sheet, so whenever receipts and statements start piling up, remember this: your net worth is just a number, influenced by numerous things like interest rates, housing markets and decisions made in rooms you’ll never see. Your worth as a person comes from how you treat others, the effort you give each day, and the kindness you show even when it’s easier not to. These two measure completely different things, and mixing them up is a very human, understandable mistake, especially when the economy seems intent on making that confusion harder to avoid.
Let the budget be a tool, not a judge, and allow yourself to grieve the milestones that have passed. Build your defenses patiently and without shame, so you can rest. You’re not falling behind because you’re failing; you feel behind because the road is steeper than anyone warned, and you’re still walking it.
If this resonated, send it to a friend who has been carrying the same weight in silence. Sometimes the most useful thing we can give one another is the reminder that it is not just us.
Disclaimer: This article is for informational purposes only and does not constitute financial or investment advice. Consult with a qualified 1 financial advisor or tax professional before making any decisions about your investments or retirement accounts
Jay Sadio, MBA